

Managing several credit card balances at the same time can make debt repayment complicated and expensive. Different due dates, minimum payments, APRs, and balances make it difficult to see exactly how much the debt costs or when it will finally disappear. A personal loan can simplify that situation by replacing several revolving balances with one installment loan and one scheduled monthly payment.
However, debt consolidation does not automatically reduce debt. It changes the structure of what you owe. Whether a personal loan improves your finances depends on the new APR, origination fees, repayment term, monthly payment, your credit profile, and what happens to your credit cards afterward. Before accepting an offer because the payment looks smaller, compare the complete cost of the new loan with the cost and repayment path of your existing balances.
Understand What Debt Consolidation Actually Does
When you use a personal loan for credit card consolidation, you borrow a lump sum and use it to pay eligible card balances. Instead of owing several credit card companies, you generally make scheduled payments on the personal loan according to its terms. The cards themselves do not necessarily close simply because their balances were paid.
That distinction matters because consolidation does not erase the original spending decisions or increase your income. If you owe $15,000 across credit cards and borrow $15,000 to eliminate those balances, you still owe approximately $15,000 before considering loan fees or other costs. The potential advantage comes from obtaining better borrowing terms and a clearer repayment structure, not from making the debt disappear.
A successful consolidation therefore requires two improvements at the same time. The new loan should make financial sense, and your spending habits must prevent the old credit card balances from returning. Without both, you can end up with the personal loan plus new credit card debt.
Compare APRs Before Looking at the Monthly Payment
The annual percentage rate is one of the most important numbers in a consolidation decision because it helps reflect the cost of borrowing. Credit cards can carry relatively high APRs, while qualified borrowers may sometimes receive lower rates on personal loans. But available rates vary considerably based on the lender, borrower, loan, and other factors.
Suppose you have several credit cards with high rates and receive a personal loan offer at a substantially lower APR. That difference could potentially reduce the amount of interest paid while you eliminate the balance. If the personal loan APR is similar to your existing card rates, however, the financial benefit may be much smaller.
Compare actual offers rather than advertised starting rates. A lender may promote attractive rates that are available only to borrowers meeting particular qualifications. The number that matters is the APR and terms offered to you after the lender evaluates your application.
A Lower Monthly Payment Can Hide a Longer Loan
One of the most attractive features of consolidation is the possibility of reducing the total amount you must pay each month. That can improve cash flow, especially when several credit card minimums have become difficult to manage.
But lenders can create a smaller monthly payment by extending repayment over a longer period. A loan spread across five years will generally require smaller scheduled payments than the same principal repaid over three years, all else equal. The longer term can also create more time for interest to accumulate.
Compare both the monthly payment and the total repayment amount disclosed for the loan. If consolidation saves $250 per month but keeps you in debt several years longer, decide whether the additional flexibility justifies the overall cost. A comfortable payment is useful, but becoming comfortable with debt indefinitely is not the objective.
Your Credit Profile Influences the Offer
Personal loan rates and approval decisions can depend on your credit history, income, existing debts, loan amount, lender requirements, and other underwriting factors. Borrowers with stronger profiles may have access to more competitive terms, while others may receive expensive offers or may not qualify.
Before applying broadly, review your credit reports for accuracy and understand your current financial position. Correcting legitimate errors can be important regardless of whether you proceed with consolidation. You should also know your current debt balances and monthly obligations so you can evaluate whether a proposed loan actually improves the situation.
Do not assume that qualifying for a personal loan means the loan is financially beneficial. Approval tells you that a lender is willing to extend credit under particular terms. Your job is to determine whether those terms improve your finances compared with the alternatives.
Decide What to Do With the Paid-Off Cards
After consolidation, you need a plan for the credit cards that now have little or no balance. Some borrowers consider closing them immediately to remove temptation, while others keep accounts open for specific purposes.
Closing a credit card can affect your credit profile in different ways, including by changing available revolving credit and account history considerations. The impact depends on your overall credit file, so there is no universal rule requiring every paid-off card to be closed.
If keeping the cards creates a serious risk of rebuilding debt, behavioral protection may matter more to you than optimizing every credit metric. You could remove cards from your wallet and digital payment methods, disable unnecessary recurring charges, or use other controls while keeping your repayment strategy focused.
Build a Budget Before Signing the Loan
A consolidation loan should fit into a budget that works without additional borrowing. Calculate your take-home income and subtract housing, utilities, food, transportation, insurance, required debt payments, and other essential expenses.
Then insert the proposed personal loan payment. If the budget still leaves enough room for emergencies, irregular expenses, and reasonable discretionary spending, the payment may be sustainable. If paying the loan requires using credit cards for groceries or utilities, the consolidation plan is already showing a structural problem.
Run the budget using a difficult month, not your best month. If your income varies, use a conservative estimate. A loan payment that only works when overtime, commissions, or bonuses are unusually high can become difficult to maintain when income returns to normal.
Keep Some Emergency Savings While Paying the Loan
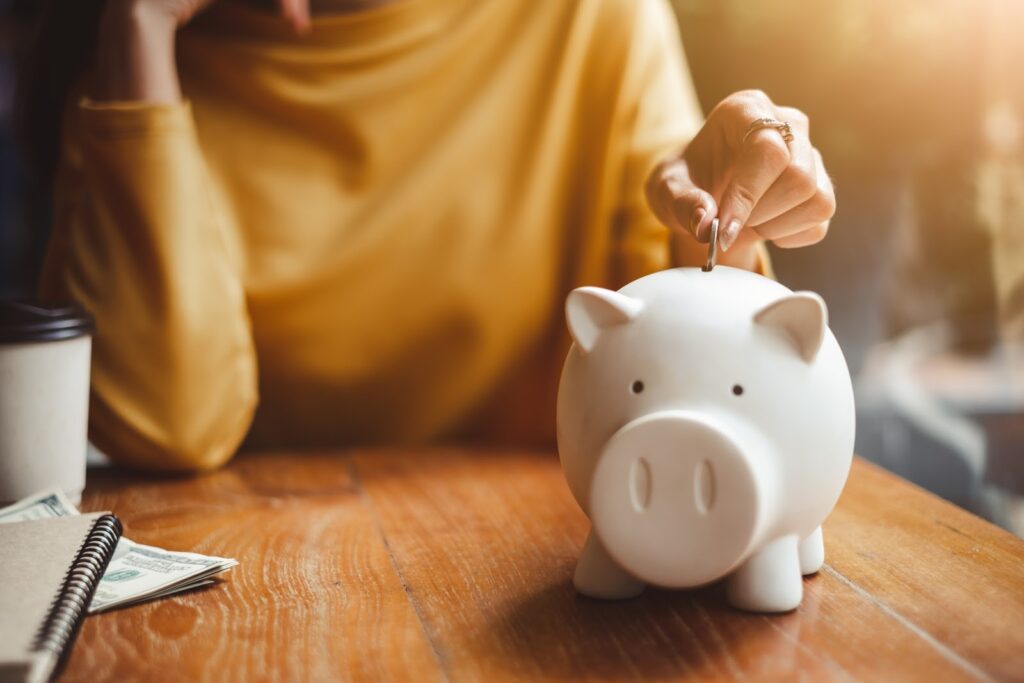
It can be tempting to send every available dollar toward the new loan because you want to eliminate the debt quickly. But maintaining no emergency savings can send you back to credit cards when an unexpected expense arrives.
Suppose you have $3,000 in savings and a new consolidation loan. Using the entire $3,000 for an additional loan payment may reduce debt faster, but a $1,500 car repair next month could force you to charge the expense. You would be recreating revolving debt immediately after consolidation.
The appropriate emergency reserve depends on your household, but having some accessible cash can protect the repayment plan. Once you have a reasonable buffer, additional money can be directed toward faster debt reduction if the loan allows extra payments without unwanted consequences.
Check for Prepayment Rules
If you plan to pay the personal loan faster than scheduled, review the loan agreement for any relevant prepayment provisions. Many borrowers assume they can simply make extra payments whenever they want, but it is important to understand exactly how the lender handles them.
Confirm whether additional payments reduce principal as intended and whether any fees or restrictions apply. Also verify that you understand how to designate extra amounts if the lender provides specific payment instructions.
A consolidation loan becomes more flexible when you can make the required payment during tighter months and accelerate repayment during stronger months. But that strategy should be based on the actual contract rather than assumptions about how the lender processes payments.
A Nonprofit Credit Counseling Option May Also Be Worth Exploring
Borrowers struggling with multiple credit card payments may also consider speaking with a reputable nonprofit credit counseling organization. Depending on the situation, counselors may help review the budget, explain repayment options, or discuss whether a debt management plan is appropriate.
Debt management plans are different from taking out a consolidation loan. They can have their own requirements, costs, effects on account access, and repayment structures. Understand the details before enrolling.
Be especially cautious with companies making aggressive promises about eliminating debt for pennies on the dollar or guaranteeing specific results. Debt relief and debt settlement services are different from straightforward consolidation, and the financial and credit consequences can be significant.
Make Consolidation the Last Time You Move the Debt
A personal loan can be an effective tool when it replaces expensive revolving debt with a lower-cost, structured repayment plan. It can simplify your finances, provide a clear payoff schedule, and potentially reduce interest when the terms are genuinely better.
But consolidation cannot compensate for a budget that consistently spends more than household income. Before signing, calculate the APR, fees, repayment term, total cost, and monthly payment. Make sure the payment fits your budget while leaving room for necessary expenses and at least some financial cushion.
Most importantly, create a plan for the credit cards after their balances are paid. The objective is not to move debt from one lender to another every few years. It is to use consolidation as a transition from expensive revolving balances toward a financial system where credit card debt no longer controls your monthly cash flow.
 What Happens to Your Finances After Losing Your Job? 30-Day Plan <p class='sec-title' style='line-height: normal; font-weight: normal;font-size: 16px !important; text-align: left;margin-top: 8px;margin-bottom: 0px !important;'> Follow this practical 30-day money plan to protect savings, prioritize bills, manage debt, and extend your financial runway. </p>
 Is Pet Insurance Worth the Monthly Cost? Calculate This First <p class='sec-title' style='line-height: normal; font-weight: normal;font-size: 16px !important; text-align: left;margin-top: 8px;margin-bottom: 0px !important;'> Learn how premiums, deductibles, reimbursement rates, coverage limits, and emergency savings affect the real value of pet insurance. </p>
 How Much Money Should You Have Left After Paying Monthly Bills? <p class='sec-title' style='line-height: normal; font-weight: normal;font-size: 16px !important; text-align: left;margin-top: 8px;margin-bottom: 0px !important;'> Learn how to evaluate cash flow, savings, debt, irregular expenses, retirement, and financial breathing room. </p>